






















PART ONE
By MAHMOOD SANGLAY
The presumed tension between piety and prosperity is not consistent with the Islamic tradition. The Qur’an does not sanctify poverty, nor does it make riches proof of divine favour.
Instead, the Qur’an and the Prophet Muhammad (ﷺ) admonish lawful enterprise that enables virtuous conduct: provide without dependence, create useful work, finance worship and learning, and circulate resources among families and communities.
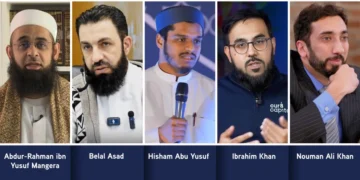
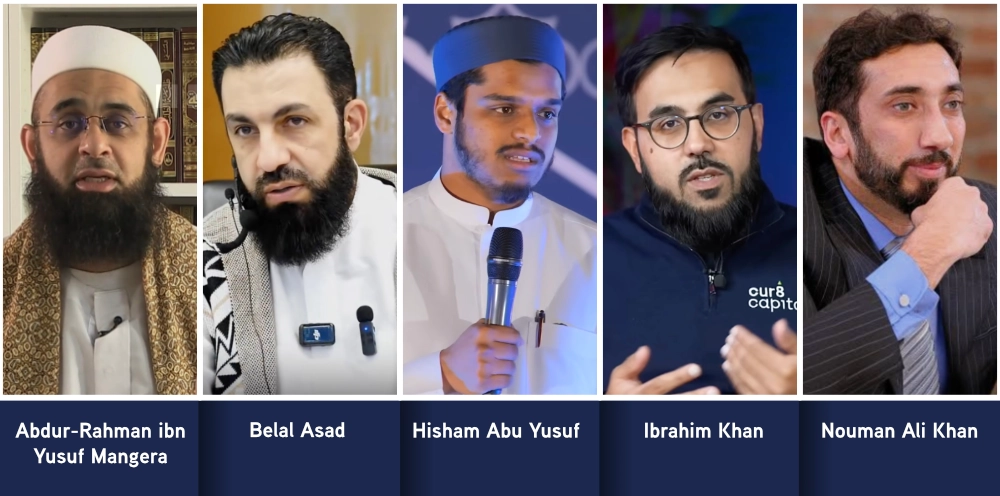
In this two-part series, the teachings of Mufti Abdur-Rahman ibn Yusuf Mangera, Belal Asad, Hisham Abu Yusuf, Ibrahim Khan, and Nouman Ali Khan are read alongside contemporary scholarship on Islamic wealth management. These sources argue that successful entrepreneurship can be commendable precisely because ownership is a trust rather than an entitlement. Through the example of Abdur-Rahman ibn Awf, it explores how initiative, commercial competence and generosity can reinforce one another. The wealthy Muslim is therefore not praised for accumulation alone, but for turning productive capacity into family security, social opportunity and service to Allah.
A duty before an achievement
Muhammad Abdullah’s study “Islam, Spirituality and Wealth: Islamic Framework of Wealth Management” (pp. 43–50) of Islamic spirituality and wealth captures this qualified approval. The Qur’an condemns hoarding, (Sura 102 and 104:2) yet describes wealth as a bounty that may be deployed in righteous causes. Abdullah notes that Zakah and Hajj require financial capacity, while sadaqah, waqf and charitable bequests depend upon somebody first generating a surplus. A society that collectively shuns wealth would struggle to sustain families, mosques, education and welfare. His conclusion is deliberately balanced: neither affluence nor poverty produces spiritual excellence by itself. Intention, conduct and the treatment of wealth determine its moral value.
Belal Asad translates that principle into a household duty. Drawing on the Prophetic teaching that the giving hand is better than the receiving hand, he argues that financial independence is preferable to avoidable dependence. A Muslim should work, use available abilities and resist turning reliance on Allah into an excuse for passivity. Provision remains with Allah, but tawakkul does not cancel effort. It requires a believer to use the means Allah has provided.
That effort begins with responsibility, not personal display. Asad emphasises that a spouse, children and other dependants have the first claim on one’s earnings. Maintenance of the family is both an obligation and a form of charity. His reading of Qur’an 4:9 also makes provision across generations a religious concern: believers should fear leaving vulnerable children without adequate resources. Entrepreneurship can therefore serve an immediate moral purpose. It gives a Muslim the means to meet present duties, build resilience and leave an orderly estate rather than transferring preventable hardship to others.
Nafis Alam and his co-authors, in their paper “Islamic Wealth Management” (pp. 452–456) place the same responsibility within a complete wealth-management cycle. Islamic wealth management covers intention, lawful acquisition, growth, risk management, spending, succession and the rights of the poor. Income meets current needs; wealth consists of accumulated savings and productive assets. Building wealth is commendable because it allows a household to move beyond subsistence, preserve resources and plan for future obligations. Yet ownership remains subordinate to trusteeship: wealth ultimately belongs to Allah, and the human holder may not spend it merely according to appetite.
Enterprise that serves society
Nouman Ali Khan extends the argument from the household to the economy. His Qur’anic exposition rejects the habit of placing worship in one compartment and trade, careers and markets in another. The Qur’an repeatedly directs human beings to travel through the earth, seek Allah’s bounty, use natural resources and engage in exchange. Khan reads these passages as encouragement to explore, build and trade ethically. Commercial initiative creates more than private profit. A business-friendly culture can generate employment, widen the middle class, develop skills and expand the revenue through which public needs are supported.
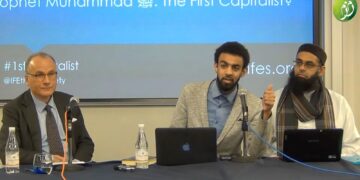
The focus of Khan here is Qur’anic imagery of investment, business development, travel and the pursuit of Allah’s bounty.
Here Khan focuses on how entrepreneurship can widen employment and the middle class, stimulate innovation and support public infrastructure.
This wider benefit explains why successful entrepreneurship has social value in Islam. The Jersey Finance Report, (pp. 8–11, 26–27 and 34–35) on global attitudes to Islamic wealth management states that permissible wealth creation may be treated as part of worship when creation and distribution remain balanced. Its survey of 2,048 respondents in 17 jurisdictions also shows that this is not merely an historical ideal. About 62% said they would always choose a Shari’ah-compliant investment even if it underperformed a conventional alternative. Just over 96% regarded lifetime philanthropy as important, 79% had already made significant contributions and 83% considered giving in accordance with faith important. Muslim investors are not simply seeking religious labels for conventional accumulation. Many want portfolios, succession arrangements and philanthropy to express a coherent moral commitment.
The life of Abdur-Rahman ibn Awf gives that commitment a human form. When he reached Madinah as a migrant without property, his Ansari brother Sa’d ibn al-Rabi’ offered him substantial assistance. Abdur-Rahman declined the gift and asked to be shown the market. Ibrahim Khan and Mufti Abdur-Rahman ibn Yusuf treat this as a model of self-reliance, confidence and action. He began with ordinary goods and small transactions, learned the market and expanded through repeated trade. His achievement did not rest on inherited advantage or an instant windfall, but on competence, disciplined effort and trust earned over time.
In this insert Ibrahim Khan focuses on Abdur-Rahman ibn Awf’s refusal of a handout, entry into the market and the ethic of self-reliant action.
The mufti also discusses the “show me the market” model of Abdur-Rahman ibn Awf: starting small, avoiding debt-heavy expansion and coupling enterprise with sadaqah.
The accounts also portray enterprise as a community-building activity. Ibrahim Khan describes Abdur-Rahman ibn Awf inspecting goods, disclosing defects, pricing fairly and maintaining records. He reportedly extended interest-free loans to smaller traders, sometimes forgave debts and supported those who could not trade through direct charity. Capital was not used to trap borrowers or eliminate possible competitors. It enabled others to enter the market. This approach anticipated the principle emphasised by Mohamed Gadhoum (pp. 20–21). Islamic markets should reward genuine exposure to risk and liability while resisting the concentration of wealth among a few.
Abdur-Rahman ibn Awf’s generosity was possible because he continued producing wealth. Reports of caravans donated for communal benefit dramatise the scale, but the central point is the relationship between enterprise and giving. Charity was not a substitute for business and business was not an escape from charity. One sustained the other. The Prophetic assurance that sadaqah does not diminish wealth gave his commercial success an outward direction. His resources helped debtors, traders, families and the wider community.
Khan reiterates the Prophetic teaching that charity does not diminish wealth and protects against calamity.
The measure of stewardship
You may also want to read




Gadhoum (pp. 14–17) consequently broadens the meaning of wealth beyond money. Material assets are one form of maal, but knowledge, wisdom and beneficial intellectual work are also riches. Knowledge helps human beings discover resources, overcome scarcity and create social benefit. Hisham Abu Yusuf’s warning against get-rich-quick schemes fits this framework. Young Muslims should develop a valuable skill in fields such as design, plumbing, security or another useful trade. Durable prosperity grows from knowledge applied to real needs, not from promotional fantasies promising effortless returns.
Hisham Abu Yusuf, with characteristic charisma, rejects get-rich-quick schemes and advocates for building durable, useful skills.
Becoming wealthy is therefore commendable when it increases a Muslim’s capacity for stewardship. It can free a family from unnecessary dependence, finance worship, create work, transfer knowledge, support institutions and place capital at the service of justice. Poverty deserves compassion and carries no moral disgrace; wealth carries no automatic honour. But lawful, competent and generous entrepreneurship turns private means into public benefit. In that sense, the wealthy Muslim is commended not for having more, but for accepting more responsibility.
In Part Two next week we look at the spiritual, ethical and practical conditions that turn wealth building into responsible stewardship—and the dangers that arise when wealth begins to govern its owner.