





















PART TWO
In this concluding part, the case for Muslim prosperity is tested by its limits. Islam permits profit and encourages productive initiative but never grants wealth moral autonomy.
Drawing on the various religious scholarly sources examined in Part One, we examine when wealth building acquires barakah rather than becoming a source of spiritual loss. The entrepreneur remains a trustee before Allah, answerable for the business, each transaction, the treatment of people and the distribution of gains. Taqwa, skill, honest disclosure, shared risk, prudent preservation, Zakah and family provision form one ethical system, alongside warnings against riba, speculative shortcuts, waste, exploitation and Qarun’s self-glorification. Abdur-Rahman ibn Awf supplies the decisive lesson: success is commendable only while the owner governs wealth, rather than allowing wealth to govern the owner.
Purpose before profit
The first condition is clarity of purpose. Mohamed Gadhoum describes human beings as trustees rather than absolute owners of resources. They will be accountable for how wealth was acquired, accumulated and distributed. This changes the entrepreneur’s central question. Profit remains legitimate, but it is not sovereign. Business decisions must be judged by their effects on the owner, workers, customers, dependants and society, as well as by their financial return. (Mohamed A. Gadhoum, “Wealth from the Shariah Perspective,” pp. 19–20.)
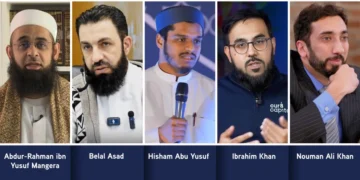
Belal Asad places taqwa at the beginning of wealth building. Obedience to Allah and avoidance of prohibited conduct are not practices added after commercial success; they govern the route towards it. He couples tawakkul with proactive effort, planning and use of available resources: the believer ties the camel and trusts Allah. Consistent repentance, maintaining family ties, gratitude and charity cultivate the spiritual conditions associated in Quran and hadith with expanded provision and a good life. Asad also treats an early, organised start to the day as useful discipline, while candidly noting that narrations commonly cited about its special blessing are weak. The practical merit does not require an exaggerated religious claim.
The focus of this clip is on planning, purposeful effort, use of lawful means, tawakkul and remembrance as foundations of provision.
Ibrahim Khan similarly identifies du’a, istighfar, gratitude, charity and productive mornings as habits that orient effort towards Allah. These practices should not be reduced to mechanical “wealth hacks”. Supplication is worship, not a transaction that compels a particular financial outcome. Contentment corrects the illusion that wealth consists only of what is missing, while gratitude requires action, including responsible spending and sharing. Charity functions as protection against attachment and calamity, but it is not a speculative bargain with God.
The practical corollary is competence. Hisham Abu Yusuf dismisses schemes promising rapid riches and insists on developing concrete skills. Abdur-Rahman ibn Awf’s example reinforces the point. He went to the market, studied demand, built relationships, inspected merchandise and reinvested profits. Mufti Abdur-Rahman ibn Yusuf highlights the lesson of beginning with small transactions rather than financing an untested idea through a large, burdensome loan. Prudence, patience and market knowledge are elements of ihsan, the pursuit of excellence, rather than signs of weak reliance on Allah.
Competence and lawful structure
Muhammad Abdullah’s framework gives these disciplines a jurisprudential structure. Lawful wealth depends on three questions: what is being sold, how the transaction is structured and how the parties behave. Prohibited goods and services cannot become acceptable through efficient management. Transactions must avoid riba, gambling, excessive uncertainty and exploitation. Wealth should be linked to real investment or productive activity carrying genuine, diligently managed risk; money should not generate a guaranteed return simply because one party controls capital. Risk may be reduced and shared, but it cannot be shifted entirely onto the weaker participant. (Muhammad Abdullah, “Islam, Spirituality and Wealth,” pp. 44–45 and 50–53.)
This framework also requires preservation. Hifz al-maal, the protection of wealth, is one of the higher objectives of Shari’ah. Preservation does not mean hoarding cash. Abdullah argues that wealth must be protected from waste and avoidable diminution through planning, investment and careful allocation. Nafis Alam identifies Shari’ah-compliant equities, sukuk, real estate and takaful among the instruments that can support growth and risk management. The product name, however, is never sufficient. Its underlying activity, contractual structure and governance must meet the ethical purpose of Shari’ah. (Muhammad Abdullah, “Islam, Spirituality and Wealth,” pp. 50–52; Nafis Alam et al., “Islamic Wealth Management,” pp. 455–464.)
Honesty is therefore an economic asset and a religious requirement. The transcript accounts describe Abdur-Rahman disclosing defective goods and reducing their price rather than hiding the flaw. Transparent records kept doubtful transactions from entering his business. His interest-free assistance to traders illustrates collaboration without exploitation. Such conduct builds reputation and repeat business, but its Islamic merit does not depend on whether honesty always produces the highest immediate profit. It is required because customers and partners possess rights.
Nouman Ali Khan sharpens the warning through the Quranic figure of Qarun. Wealth becomes destructive when success is attributed entirely to personal brilliance, other people become assets or obstacles, and commercial power captures political authority. Fraud, bribery and collusion between wealthy interests and officials do more than transfer money unlawfully; they corrode trust and can destabilise society. Khan also places responsibility on consumers. Manipulative marketing thrives on envy, compulsive consumption and status anxiety. Salah repeatedly interrupts this absorption, returning the worshipper to accountability before Allah and restoring balance.
This clip focuses on Qarun’s cut-throat, manipulative and hyper-individualistic model of wealth, contrasted with a believer’s duties to others.
You may also want to read


The danger is thus both structural and inward. Extravagance is measured against means and duty, not simply the price of an item. Asad lists waste, ingratitude, stinginess, superstition and neglect of zakat among the behaviours that strip wealth of barakah. The cure is neither performative austerity nor uncontrolled spending. It is disciplined consumption, fulfilment of others’ rights and freedom from the need to display status.
Purification and accountability
Purification and distribution complete the wealth cycle. Gadhoum distinguishes zakat from the cleansing of impermissible incidental income. Zakat is a defined obligation on qualifying wealth and supports specified classes of recipients. Purification requires identifying income arising from non-compliant sources and disposing of it for charitable benefit rather than treating it as personal profit. Waqf, sadaqah, gifts, bequests and Islamic inheritance then move resources across generations and social groups. The Jersey Finance study found that 96% of respondents were undertaking or planning succession arrangements, while 63% intended to obtain Shari’ah advice. Good intentions require legal and fiduciary structures capable of protecting heirs and carrying out Islamic obligations. (Mohamed A. Gadhoum, “Wealth from the Shariah Perspective,” pp. 21–23; Jersey Finance, “Global Attitudes to Islamic Wealth Management,” pp. 30–35.)
Family claims remain prior to optional generosity. A person should not give impressively in public while neglecting maintenance, debt or inheritance duties in private. Belal Asad’s ordering of expenditure and the research report’s discussion of fara’id, wasiyyah and waqf point to the same principle: distribution is governed, not improvised. Responsible wealth building includes wills, accurate records, professional advice and timely zakat. (Jersey Finance, “Global Attitudes to Islamic Wealth Management,” pp. 10–17 and 30–33.)
Abdur-Rahman ibn Awf embodied the final safeguard, muhasabah. Despite extraordinary success, he reportedly feared that abundance in this life might reduce his reward in the next. He remembered companions who died with little, wept before luxury and compared what he accumulated with what he gave. This was not hostility towards enterprise. It was vigilance against the entrepreneur becoming possessed by his possessions.
Islam therefore does not offer a formula guaranteeing that devotion will make every Muslim rich. It offers a standard by which wealth may become beneficial: lawful production, skilled work, shared risk, honest exchange, prudent preservation, family provision, purification and generous circulation. Success remains a test. The entrepreneur passes it only when material growth is matched by spiritual discipline and when private prosperity strengthens, rather than impoverishes, the community.