






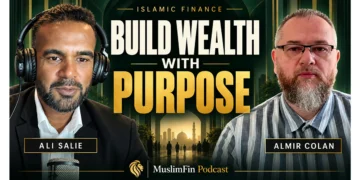




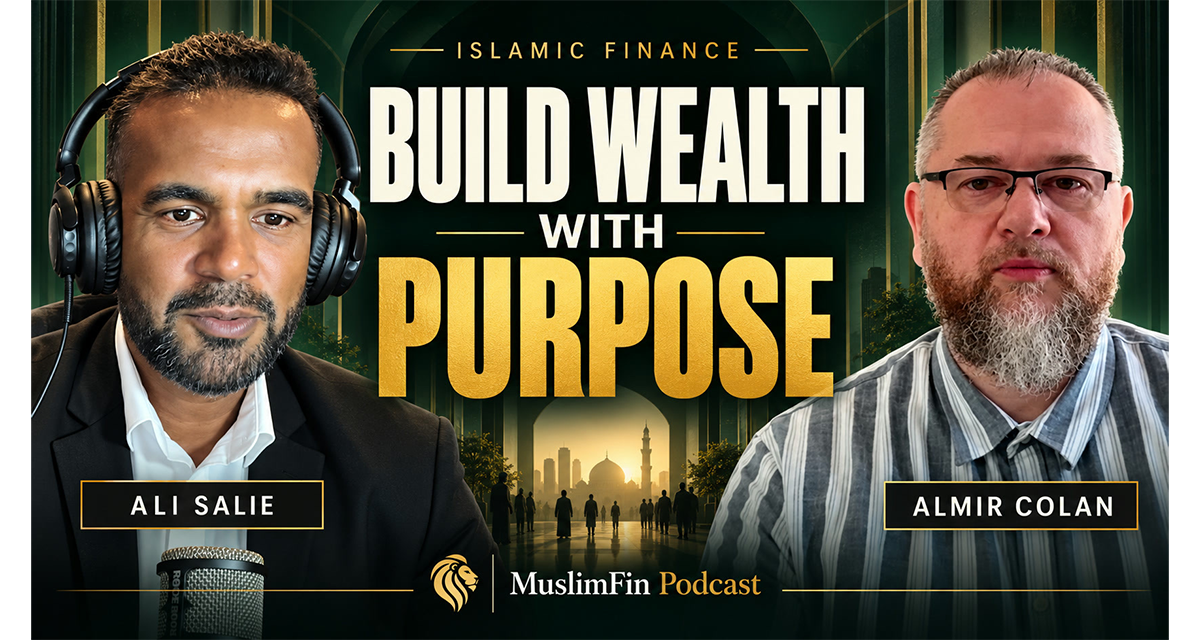

A MuslimFin conversation with Almir Colan asks what wealth should make possible, linking financial success to stronger families, responsible enterprise, useful skills and communities able to sustain the institutions they value most.
By ALI SALIE
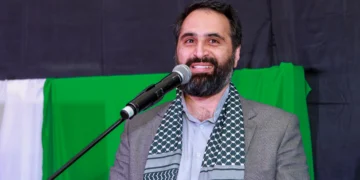
An exchange with Almir Colan asks us to judge financial success by the skills, families and communities it helps to sustain. Colan is the founder of Muslim Money Matters, an educational platform focused on Islamic perspectives in finance, business and economic leadership.
When we discuss money, the conversation often begins with a product. We want to know which account to open, how to finance a home or where to invest. These are necessary questions. Yet they can leave a larger question unanswered: what do we want our financial decisions to make possible? During my recent MuslimFin Podcast conversation with Colann we kept returning to the relationship between personal ambition and the wellbeing of the community around us.
Colan brought a perspective shaped by growing up in Bosnia and later living in Australia. He described how experiences of upheaval influenced his understanding of what a community needs. His interest in Islamic finance grew alongside questions about how economies work and how families secure a future. The discussion challenged a narrow picture of financial success, inviting us to think about the institutions, relationships and practical capabilities that wealth can support.
A stronger family within a stronger community
I asked Colan where an ordinary family trying to make better financial choices should begin. His answer widened the discussion beyond the household balance sheet. Families move through different stages: establishing a home, developing a career, starting an enterprise and eventually deciding how to use accumulated resources. Across those stages, financial arrangements can help people remain connected to the places and institutions through which community life happens.
He made a distinction that deserves attention: it is possible to produce successful individuals while leaving the surrounding community fragile. A family may improve its own circumstances while the school, neighbourhood or network on which it depends becomes less secure. Colan argued that the purpose of personal success should include strengthening that wider community. The benefits then return to the individual through a healthier environment in which to live and practise their faith.
For me, this raises a practical question about how we define progress. Alongside asking whether our finances are improving, we can ask what our decisions are helping to sustain. That does not require every household to establish a major institution. It does require noticing the connection between private choices and shared needs. A community becomes stronger through people who understand those connections and take their responsibilities seriously, within their means.
Looking more closely at what we consume
When I asked where Islamic finance might go in the coming years, Colan spoke about real impact. He wanted the conversation to reach the production of goods and services, and the people making decisions along the way. His question was direct: who produces what we consume, and do their decisions reflect the values we care about? Finance enters this discussion because capital helps determine what gets built and whose priorities receive support.
This is a useful challenge for anyone running a business. A product reaches a household through decisions about materials, labour, pricing, reliability and service. Those decisions have human consequences. Profit matters to the survival of an enterprise, but the conversation asks us to look carefully at the usefulness of what the enterprise delivers. A successful sale does not, by itself, tell us whether a customer has been well served.
Colan cautioned against remaining a consumer who simply hopes somebody else will make responsible decisions. His wider argument encouraged participation in production and the choices behind it. We can take that seriously without pretending every buyer can investigate every supplier. Business owners can examine their own practices. Professionals can ask better questions within their area of responsibility. Families can build understanding over time, recognising that informed choices require evidence rather than attractive labels or assumptions.
For those of us discussing finance publicly, there is a responsibility here too. We should explain the purpose of a decision alongside its mechanics, and be clear about the limits of what we know. A conversation about values loses credibility when it relies on exaggerated claims. Asking how a business works, who benefits and what evidence supports its promises can turn an abstract discussion into a more useful one. It is a habit worth teaching early and practising consistently in everyday life.
Give ambition something useful to do
Our final exchange turned to young people entering education, work and enterprise. I asked what advice Colan would offer those beginning that journey. He placed competence at the centre of his response: become good at something with a real application, understand an industry and recognise the problems that need solving. That is an encouraging message for young people who feel pressure to demonstrate financial success before they have had time to develop their abilities.
One sentence stayed with me: “Money is there to serve you, not to lead you as a master.” Colan described wealth as something that can amplify existing knowledge and capability. That makes the development of the person an essential part of the financial conversation. If resources increase what we can do, we should care deeply about what we know, how we exercise judgement and what we intend to contribute.
You may also want to read


His advice joined religious understanding with knowledge of the world and deep practical skills. The ambition he encouraged was purposeful: understand what is happening around you and become excellent at work that matters. For a student, that might begin with taking a chosen discipline seriously. For someone already employed, it might mean identifying a gap in their competence and addressing it. These are applications of the conversation, not promises of a particular income or outcome.
A question worth bringing home
The thread connecting these exchanges is responsibility. A household needs sound financial decisions, a business needs customers it serves well, and a community needs people capable of building and maintaining useful institutions. Colan’s argument connects those needs. It gives us a way to discuss wealth that includes ambition while asking what that ambition produces for others.
We can begin the next family conversation about money with a simple question: what are we trying to make possible? The answer may involve security, learning, enterprise or a contribution to community life. Naming that purpose helps us judge the choices that follow. It also gives the next generation a richer understanding of success: resources joined to knowledge, responsibility and work that brings a real benefit.
Ali Salie is the co-founder and Advisory Partner with the MuslimFin Family office.
- This article is for general education only. Personal financial decisions require advice suited to individual circumstances.